Suburban and planned communities
HOA dues and district assessments when present belong in the full housing budget.
Clay County home financing
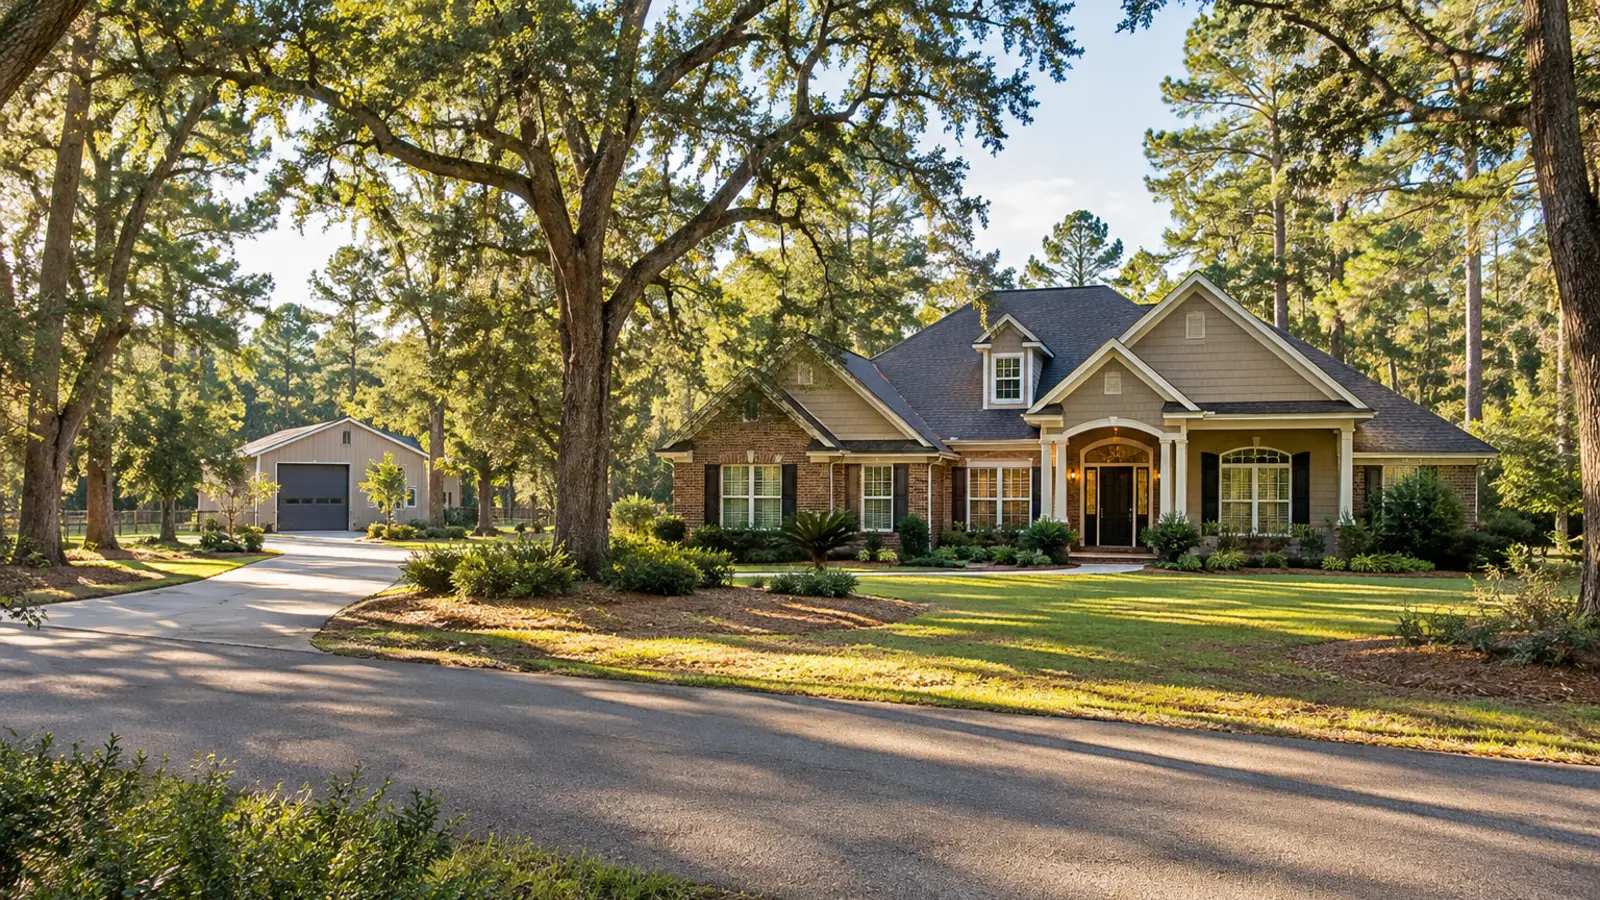
Clay County includes established neighborhoods, planned communities, larger lots and less-urban properties. Utilities, acreage, condition and association costs can change the mortgage conversation from one address to the next.
Market overview
A balanced Clay County review connects the borrower’s budget with the property’s actual features. That can mean checking flood information, determining whether utilities are public or private, identifying association or district costs and allowing enough time to evaluate acreage, outbuildings or repairs.
Housing characteristics
HOA dues and district assessments when present belong in the full housing budget.
Acreage, workshops and accessory structures may require property-specific appraisal and program review.
Some properties use private systems, and the applicable inspection or documentation needs depend on the loan and property.
Use official mapping for the exact parcel and obtain insurance guidance early.
Financing considerations
Confirm public water and sewer versus well and septic before the loan review is far along.
Discuss acreage, barns, workshops or other structures before choosing a program.
Check flood-zone information and address-specific insurance costs.
Include HOA dues and any district assessments in the payment conversation.
Allow time to resolve appraisal repairs or property-condition questions.
Property types
Condition, insurance, taxes and any association costs shape affordability.
Land use, access, outbuildings and comparable sales may need additional review.
Dues, district assessments and future tax expectations deserve attention.
Construction type, title status, foundation and program eligibility must be evaluated for the specific home.
Programs worth exploring
A broad option for many eligible primary-home, second-home and investment scenarios.
Learn about this optionGovernment-insured financing for eligible primary-residence purchases.
Learn about this optionA benefit for eligible military borrowers purchasing an appropriate primary residence.
Learn about this optionFlorida programs may be worth reviewing when current borrower, property and funding rules align.
Learn about this optionNew construction
For a new Clay County home, review builder deposits and incentives, estimated completion, rate-lock choices, future taxes, HOA or district costs and insurance. The best comparison uses the same price, down payment and closing assumptions.
Local homebuyer questions
Ask the seller and Realtor, then verify through available county and utility records. Documentation needs vary by property and program.
It can. The lender and appraiser may consider how the property is used, whether the land is typical for the area and the value of improvements.
Clay County provides flood and FEMA information plus a parcel-based Flood Zone Helper. Insurance and lender requirements still depend on the specific transaction.
Not always. Construction date and type, title, foundation, condition, land ownership and selected program can all matter.
Nearby market guides
Plan with local context