Planned communities
Association dues and district assessments may be part of the ongoing housing cost and should be identified early.
St. Johns County home financing
St. Johns County buyers may compare established communities, new construction, coastal property and planned developments. The useful question is how the specific address affects the complete financing plan.
Market overview
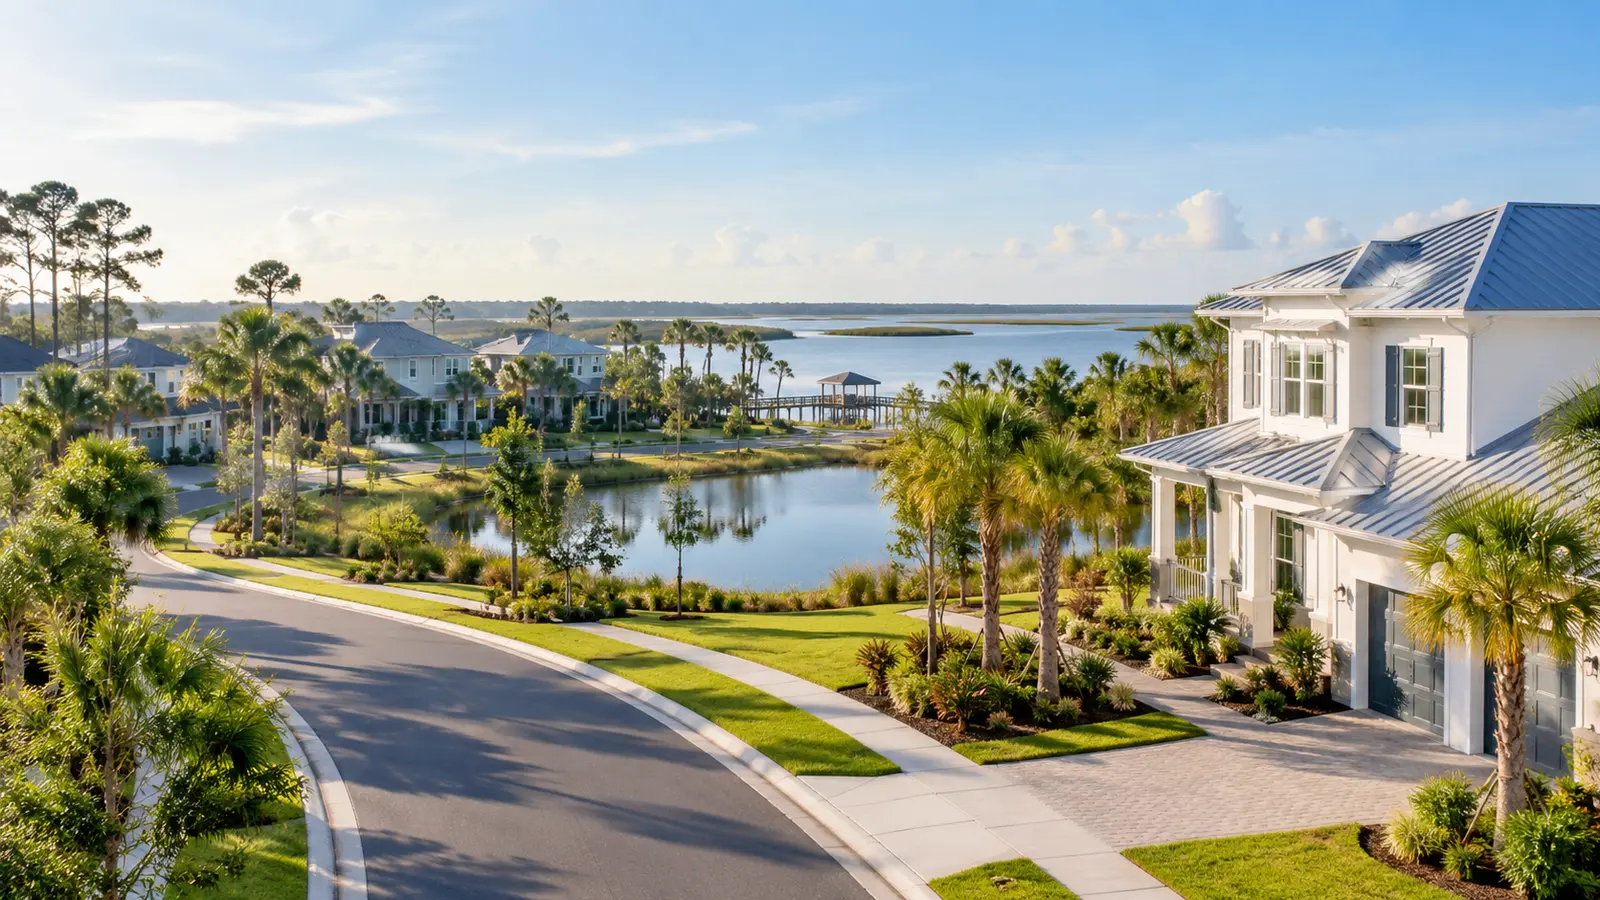
A purchase in St. Johns County can involve association dues, community development district assessments, insurance, flood information, new-construction timing and future property-tax expectations. Reviewing those items alongside the loan—not after it—creates a more realistic budget.
Housing characteristics
Association dues and district assessments may be part of the ongoing housing cost and should be identified early.
Builder contracts, deposits, incentives, completion dates and rate-lock decisions deserve a side-by-side review.
Flood information, wind exposure and insurance availability can vary by address.
Roof age, systems, condition and insurance eligibility may matter even when the home is not near the coast.
Financing considerations
Estimate the future tax picture instead of relying only on the seller’s current bill.
Identify HOA dues and any CDD or non-ad valorem assessments.
Obtain address-specific homeowners and flood-insurance information early.
For new construction, compare builder incentives with total financing cost and fit.
Confirm whether the property is a condo, townhome or fee-simple home because legal structure can affect review.
Property types
Include dues and district assessments when comparing monthly affordability.
Contract timing, deposits, incentives and completion uncertainty influence the financing plan.
Flood, wind and insurance questions should be reviewed for the exact property.
Ownership structure and association documentation can affect the available options.
Programs worth exploring
A broad option for many eligible primary-home, second-home and investment scenarios.
Learn about this optionGovernment-insured financing for eligible primary-residence purchases.
Learn about this optionA benefit for eligible military borrowers purchasing an appropriate primary residence.
Learn about this optionFlorida programs may be worth reviewing when current borrower, property and funding rules align.
Learn about this optionAn alternative-documentation path for eligible self-employed buyers.
Learn about this optionNew construction
A builder’s preferred-lender credit can be valuable, but compare it with the interest-rate structure, fees, program fit, service and total cash required. Ask how completion changes, rate-lock expiration and property-tax reassessment are handled.
Local homebuyer questions
A community development district may impose assessments that appear on the property-tax bill. Confirm the amount and duration for the specific property with official records.
Use it as one reference, not the only estimate. Ownership changes, assessed value, exemptions and new construction can change future taxes.
No. Requirements depend on the address, flood determination, lender and insurance considerations.
Yes. Compare incentives, rate and fee structure, total cash, loan fit and service using the same transaction assumptions.
Nearby market guides
Plan with local context